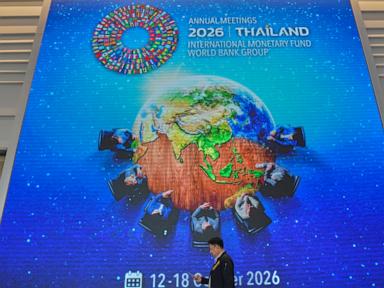
You cannot grow your way out of a $40 trillion hole by hoping for a lucky quarter. That was the blunt reality Kristalina Georgieva laid on the table in Bangkok during the October 2026 IMF and World Bank annual meetings. While wealthy nations keep leaning on growth forecasts and political optimism, the math has turned unforgiving.
When rich countries run massive deficits year after year, the shockwaves don't stay inside Washington or Brussels. Borrowing costs climb for everyone. Developing economies get squeezed out of affordable credit. Global economic pressure builds quietly first, then all at once. In related developments, read about: Why El Niño Breaks Supply Chains And Insurance Before Factories Even Notice.
Most people hear "national debt" and tune out because it sounds like an abstract spreadsheet problem for finance ministers. Honestly, it's not. Higher sovereign borrowing costs bleed into bond yields, corporate loans, and everyday household budgets across the world. When the IMF October 2026 World Economic Outlook projects global growth around 3.1 percent in 2026 with risks tilted to the downside, fiscal discipline stops being a textbook talking point. It becomes survival.
http://googleusercontent.com/lmdx_content/AnmddzPusTMyPsRfRssUhsDIonPdjMcdKeSRpsEkPMosuwglXdQAxerRqbnCGmjbngbIgododTPtpFYtBSwOscYosojYvdFHFbKoPhhqAUzbZDHoIisfUPJPCtcKTeLpolkNcAUPEHBsiZJMREibsQdqpNQhYSRGuBmOyhSjTytDmevvPMaRQuobeSHqdgrgRNrfUoaMApCd1688 The Economist has also covered this fascinating topic in great detail.
Why Wealthy Nations Can't Outrun the Debt Math
For years, politicians in major economies operated on a comforting shortcut. Grow faster than the interest rate, and debt ratios take care of themselves. That shortcut looks pretty shaky now.
In Bangkok, Georgieva made it clear that growth alone won't do the heavy lifting fast enough when U.S. national debt sits above $40 trillion. Even when leaders acknowledge that deficits and debt have climbed too high, wishing for a boom isn't a fiscal plan. "There is no magic," Georgieva warned. Bringing deficits down requires actual tightening.
Look at what changed over the past few years:
- Higher borrowing costs stick around. Policy rates and term premia are well above pre-pandemic norms, pushing debt-service bills higher in advanced economies.
- Spending demands keep piling up. Aging populations, higher defense outlays—especially in Europe—and energy security or climate transition needs are all pulling on the public purse at once.
- Markets are less patient. Bond investors punish sloppy fiscal drift faster than they used to, leaving governments with thinner margins for error when shocks hit.
I've watched plenty of budget debates where lawmakers treat fiscal restraint like political poison. Maybe it is at the ballot box. Still, pretending interest rates will magically drop back to rock-bottom levels or that AI productivity gains will automatically rescue every balance sheet is a gamble. AI could lift trend growth if expectations pan out, sure. Counting on a technological bailout before fixing spending habits is backwards.
What People Get Wrong About National Debt
A common myth is that a country issuing its own currency can borrow endlessly without consequence. Up to a point, maybe. Past a certain threshold, higher yields ripple through mortgages, business credit, and asset prices, while crowding out room to respond when a real crisis strikes.
Another misconception is that tightening budgets automatically kills growth overnight. Badly designed austerity hurts. Smart fiscal adjustment—trimming wasteful subsidies, prioritizing high-return public investment, and broadening revenue bases without strangling productive work—looks very different from slash-and-burn cuts.
How Big-Country Deficits Squeeze Low-Income Economies
When wealthy nations borrow heavily to fund big deficits, low-income countries feel the squeeze first. It's a classic case of unequal pain.
Rich countries usually have deep domestic capital markets and reserve currencies to lean on. Poorer nations don't. When global financial conditions tighten or investors chase higher yields in safer, larger markets, refinancing gets expensive fast for emerging and developing economies.
Instead of building schools, power grids, or clinics, cash-strapped governments end up spending scarce revenue just servicing old debt. That's why officials at the Bangkok meetings pressed for better debt restructuring and refinancing terms—giving developing countries longer horizons and fairer rates so they can actually breathe and invest.
There is a real debate here, though. Critics of strict fiscal rules argue that pushing every country to tighten at the same time can drag down global demand when geopolitical supply shocks and trade frictions are already testing growth. That tension is real. You don't want to choke off recovery during a supply shock, yet letting debt snowball leaves everyone exposed when the next storm hits.
What Actually Works When Shocks Hit
When prices spike from geopolitical disruptions or supply bottlenecks, governments love reaching for broad price caps or across-the-board energy subsidies. Politically, it feels decisive. Fiscally, it's often a trap.
Findings highlighted in the IMF Fiscal Monitor and October 2026 World Economic Outlook point to a harsh trade-off: broad price-suppression measures can eat up vastly more fiscal resources—research cited by the IMF notes they can require 3 to 22 times more fiscal resources—while distorting markets and failing when buffers are already thin. Targeted, temporary support for vulnerable households does far more good per dollar spent.
Practical Steps for Policymakers and Businesses
If you're running a business, managing capital, or tracking policy for an organization, waiting for politicians to suddenly become saints isn't a strategy. Here is how to stay grounded:
- Stress-test financing against higher-for-longer rates. Don't build five-year models assuming cheap debt is coming right back. Check how your cash flow holds up if refinancing stays pricey.
- Watch sovereign bond signals, not just headlines. Rising term premia and choppy government auctions often warn of fiscal strain before an official downgrade makes the front page.
- Diversify supply and funding exposure. Geopolitical shocks and tight credit hit concentrated supply chains and single-market borrowers hardest. Keep liquidity buffers real.
- Separate short-term noise from structural shifts. Geopolitical flare-ups and cyber disruptions cause sharp spikes, while aging demographics and debt service grind away over decades. Plan for both timelines.
The global economy has shown plenty of grit through rough patches. Grit isn't a substitute for fiscal discipline, though, and kicking the bill down the road only makes the eventual reckoning steeper.