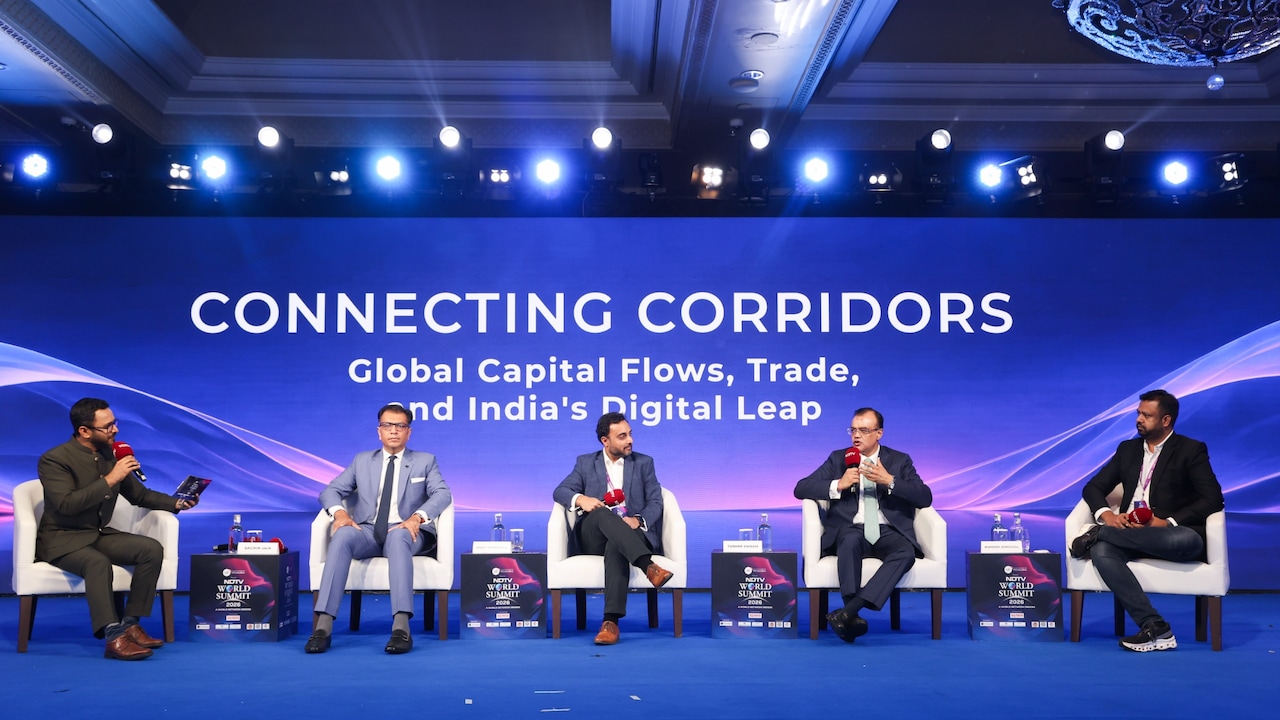
Gold cannot replace the US dollar as the backbone of global trade and finance, no matter how loudly panels at the NDTV World Summit 2026 debate the idea. Bullion makes a useful hedge against inflation and sanctions risk, yet it lacks the deep liquidity, yield, and settlement speed required to run modern commerce across borders.
Every few years, a new wave of commentators declares the greenback finished. At the October 2026 summit in New Delhi, speakers ranging from World Gold Council regional CEO Sachin Jain to banking executives and digital-asset leaders wrestled with how cross-border payments might evolve amid shifting geopolitical alliances, tokenised assets, and instant payment rails. The premise sounds dramatic. A metal with five thousand years of history stepping into the shoes of a paper currency backed by a single superpower.
Strip away the conference-stage theatre, though, and the mechanics look very different. Central banks have certainly been buying bullion at a brisk clip—averaging roughly 1,000 tonnes a year since 2021 compared with around 500 tonnes in the prior decade, with the World Gold Council's 2026 central bank survey showing 89% of respondents expecting global official gold holdings to rise over the next year. Yet buying bullion for insurance is not the same thing as using bars of gold to clear a trillion-dollar daily foreign exchange market or finance global supply chains.
The Myth of Monetary Replacement
To understand why gold hits a hard ceiling as a replacement for the dollar, look at what money actually has to do every single day. It has to act as a unit of account, a medium of exchange, and a store of value simultaneously.
Gold struggles on the first two counts. Pricing oil, shipping containers, or semiconductor wafer contracts directly in troy ounces introduces friction that businesses hate. As Tushar Vikram, Country Head and CEO of Mashreq India, pointed out during the NDTV World Summit discussion, establishing a clean, universally accepted price reference for an alternative to the dollar remains a major hurdle.
A reserve asset that sits quietly in a vault protects purchasing power over decades, but it cannot oil the daily wheels of global credit on its own.
Consider a hypothetical example to see the operational gap clearly. Suppose an electronics manufacturer in Vietnam buys components from Taiwan and sells finished goods to buyers in Europe and North America. Using US dollars—or dollar-linked clearing channels—lets that company invoice, hedge currency risk, settle suppliers, and tap short-term credit lines in one dominant liquidity pool. Trying to substitute physical gold into that chain means dealing with assay standards, vaulting fees, transport insurance, and bid-ask spreads every time value moves.
Even headlines claiming bullion had already overtaken US Treasuries as the world's top reserve asset require closer scrutiny. Surging gold prices inflated the paper value of existing central bank bars. By June 2026, foreign official holdings of US Treasuries again exceeded world gold reserves outside the United States in dollar terms, even as central banks continued adding physical ounces. Price appreciation does not equal monetary displacement.
What Central Banks Actually Want
Central bankers are not romantics chasing a return to the classical gold standard. They are risk managers reacting to a more fractured world.
When geopolitical tensions flare or financial sanctions enter policy toolkits, foreign reserves held in another nation's sovereign debt carry counterparty and access risks that physical metal inside a home vault does not. That explains why 45% of central banks in the World Gold Council's 2026 survey expected their own gold reserves to increase over the following twelve months, while 74% anticipated lower US dollar shares in global reserves over a five-year horizon.
Watch how those institutions fund their purchases, though. Roughly half of surveyed central banks pointed to domestic purchase programmes in local currency, and 38% cited selling other reserve assets. Meanwhile, storage habits are shifting quietly as well: the Bank of England still leads as a vaulting hub at 57%, followed by domestic vaults at 49% and the Bank for International Settlements at 16%, with a growing minority moving bars closer to home or spreading them across more jurisdictions.
Here is what the data reveals about reserve diversification versus dollar replacement:
| Dimension | US Dollar & Treasuries | Physical Gold |
|---|---|---|
| Yield | Pays interest through sovereign debt and money markets | Pays zero interest or dividend; incurs storage costs |
| Market Depth | Deepest, most liquid global funding and FX market | Large and liquid in spot/OTC hubs, smaller than US debt |
| Sanctions Exposure | Vulnerable to freezing or clearing restrictions | Immune to seizure once held in domestic custody |
| Trade Invoicing | Anchor currency for commodities and cross-border credit | Rarely used to price or settle routine commercial invoices |
Notice the trade-off. US Treasuries pay interest and anchor deep repo and collateral markets that global banks rely on to create dollar liquidity. Gold pays nothing. Every ounce held by a central bank represents capital that could otherwise earn yield or serve as high-grade collateral in global money markets.
Tokenised Gold and Digital Rails
If raw bullion is too clunky for modern trade, what about putting gold on a blockchain or pairing it with real-time payment networks? That question sat right at the centre of the October 2026 summit conversation.
India's digital public infrastructure—especially UPI and work around the Digital Rupee—has shown how fast domestic and cross-border retail or corridor payments can move when software strips out middlemen. Tokenised gold promises a neat bridge: fractional, programmable ownership tied to a tangible asset.
Yet tokenisation does not erase physical reality. A digital token representing a claim on a gold bar is only as trustworthy as the custodian holding the metal, the legal enforceability of the claim, and the audit trail backing the vault. If redemption is restricted or liquidity dries up during a sharp market sell-off, a tokenised wrapper can trade at a discount to net asset value right when holders need exit liquidity most.
There is also a deeper structural issue. A currency system needs an elastic supply of credit that expands and contracts with economic activity. Hard commodities like gold grow slowly through mining, regardless of whether global trade needs more settlement capacity this quarter. Tying a global payment system strictly to a finite metal reintroduces deflationary pressure during downturns—the very flaw that pushed major economies off rigid gold pegs in the twentieth century.
A Layered World Without a Single Winner
The sharper debate is not whether gold will replace the dollar. It is how countries will stitch together a multipolar payment architecture without blowing up their own trade efficiency.
Policymakers in New Delhi have already signalled a pragmatic tack rather than an ideological crusade. Using local currencies where bilateral trade flows are balanced, keeping the dollar where depth and hedging matter most, and holding gold as a strategic shock absorber makes far more sense than betting the economy on one single alternative. Even currency defence carries real trade-offs: tightening foreign exchange curbs or intervening in markets can steady an exchange rate in the short run while draining domestic banking liquidity.
For investors, corporate treasurers, and policymakers alike, the lesson is straightforward. Treat gold as a durable geopolitical and inflation hedge inside a diversified balance sheet, not as the heir to the US dollar's crown.