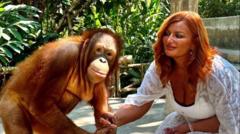
When Kelly Kershaw sat behind her counter at the Nationwide Building Society branch, processing routine withdrawals and balancing daily ledgers, the architecture of institutional trust was functioning exactly as designed. Customers walked in, handed over their passbooks or cards, and trusted that the low-level employee behind the glass window viewed their life savings with absolute professional sanctity. That trust was broken not by a sophisticated cyber syndicate deploying custom malware, but by a trusted insider who realized that human negligence and legacy oversight mechanisms left wide gaps in the audit trail. Over a period of time, Kershaw siphoned thousands of pounds—roughly thirteen thousand in total—from the accounts of elderly and vulnerable customers, using the cash to fund exotic holidays and safaris.
The story hit the headlines because of a classic modern irony: the perpetrator was exposed after broadcasting her ill-gotten travels on social media. Holiday photos of sun-drenched safaris and luxury resorts, posted openly online, contrasted sharply with the modest income of a local bank cashier. Investigators and concerned parties connected the digital dots, leading to a court-ordered payback and a prison sentence. Yet focusing purely on the vanity of the social media trail misses the structural failure that allowed a frontline retail worker to quietly loot accounts belonging to society's most financially defenseless individuals.
Fraud detection in retail banking is often treated as a grand technological fortress designed to repel external attacks from overseas hackers. Millions of pounds are funneled into firewalls, multi-factor authentication protocols, and machine learning models meant to intercept credential stuffing and unauthorized account takeovers. However, the internal threat vector—the traditional teller, the back-office clerk, or the branch administrator who possesses legitimate credentials—operates within a blind spot of institutional complacency. When a worker has authorized access to internal account management tools, the friction required to execute a small-scale theft is remarkably low.
Consider the mechanics of branch-level fraud. Unlike high-stakes financial crimes that involve complex shell companies or international money laundering networks, retail bank theft is frequently granular and painfully simple. It relies on small, incremental withdrawals that slip beneath standard automatic flag limits, or direct exploitation of customer apathy. Elderly account holders, who may check their statements infrequently or rely heavily on face-to-face interactions with branch staff they have known for years, are prime targets. When a trusted employee tells an elderly customer that a signature needs updating or a form requires a manual override, compliance checks often default to assuming good faith on the part of the staff member.
The institutional response to these internal breaches typically follows a predictable script. An investigation is launched, the offender is terminated, criminal charges are filed, and the courts order restitution. In Kershaw's case, the legal machinery ground forward, culminating in orders to pay back the stolen funds. But restitution orders against low-level offenders rarely recover the full financial or emotional cost. The money spent on safaris and holidays is gone, converted into transient experiences, leaving the financial institution to reimburse victims while absorbing the reputational damage.
More importantly, the internal risk management structures rarely change in any meaningful way. Banks prefer to treat these incidents as isolated moral failures of a single bad actor rather than symptomatic vulnerabilities of a sprawling, under-monitored retail network. Training programs emphasize anti-money laundering and cyber hygiene, yet they often gloss over the psychology of internal fraud and the reality that financial stress combined with unchecked access creates a predictable hazard.
Preventing this specific brand of internal theft requires a fundamental shift in how branch-level oversight is engineered. Dual-authorization protocols, which require two distinct staff members to sign off on discretionary cash movements or account overrides, are frequently bypassed or relaxed in busy high street branches under the banner of operational efficiency. Branch managers, pressured to meet customer throughput metrics and sales targets, prioritize speed over rigid adherence to internal controls. When efficiency supersedes verification, the margin for internal exploitation expands exponentially.
Technology can play a corrective role only if institutions are willing to deploy behavioral analytics internally, not just externally. Just as algorithms monitor customer accounts for anomalous spending patterns, internal monitoring systems can flag abnormal staff inquiry behavior, unusual account-access frequencies, or discrepancies between a retail worker's declared compensation and their lifestyle indicators. Yet privacy concerns and union pushback often stall the implementation of internal monitoring, leaving a wide gulf between what is technologically possible and what is institutionally permitted.
The public fascination with cases like this is understandable. There is a raw, poetic justice in a criminal undone by their own digital vanity, broadcasting evidence of a safari while the victims struggle to balance modest pensions. But reducing the narrative to a cautionary tale about the dangers of posting vacation photos on the internet obscures the structural vulnerabilities that made the crime possible in the first place. Until retail banking institutions treat internal access with the same paranoid rigor applied to external digital threats, the next trusted cashier with a smartphone and an expensive travel wish-list will find a way through the gaps.